There are two different "$0 down" ideas, and mixing them up costs people months.
USDA's Single Family Housing Guaranteed Loan can finance up to 100% of the appraised value for a buyer who meets income limits, credit standards, and property rules, in an area the USDA map still calls eligible. You are on title at closing. A lender, not the builder, approves you.
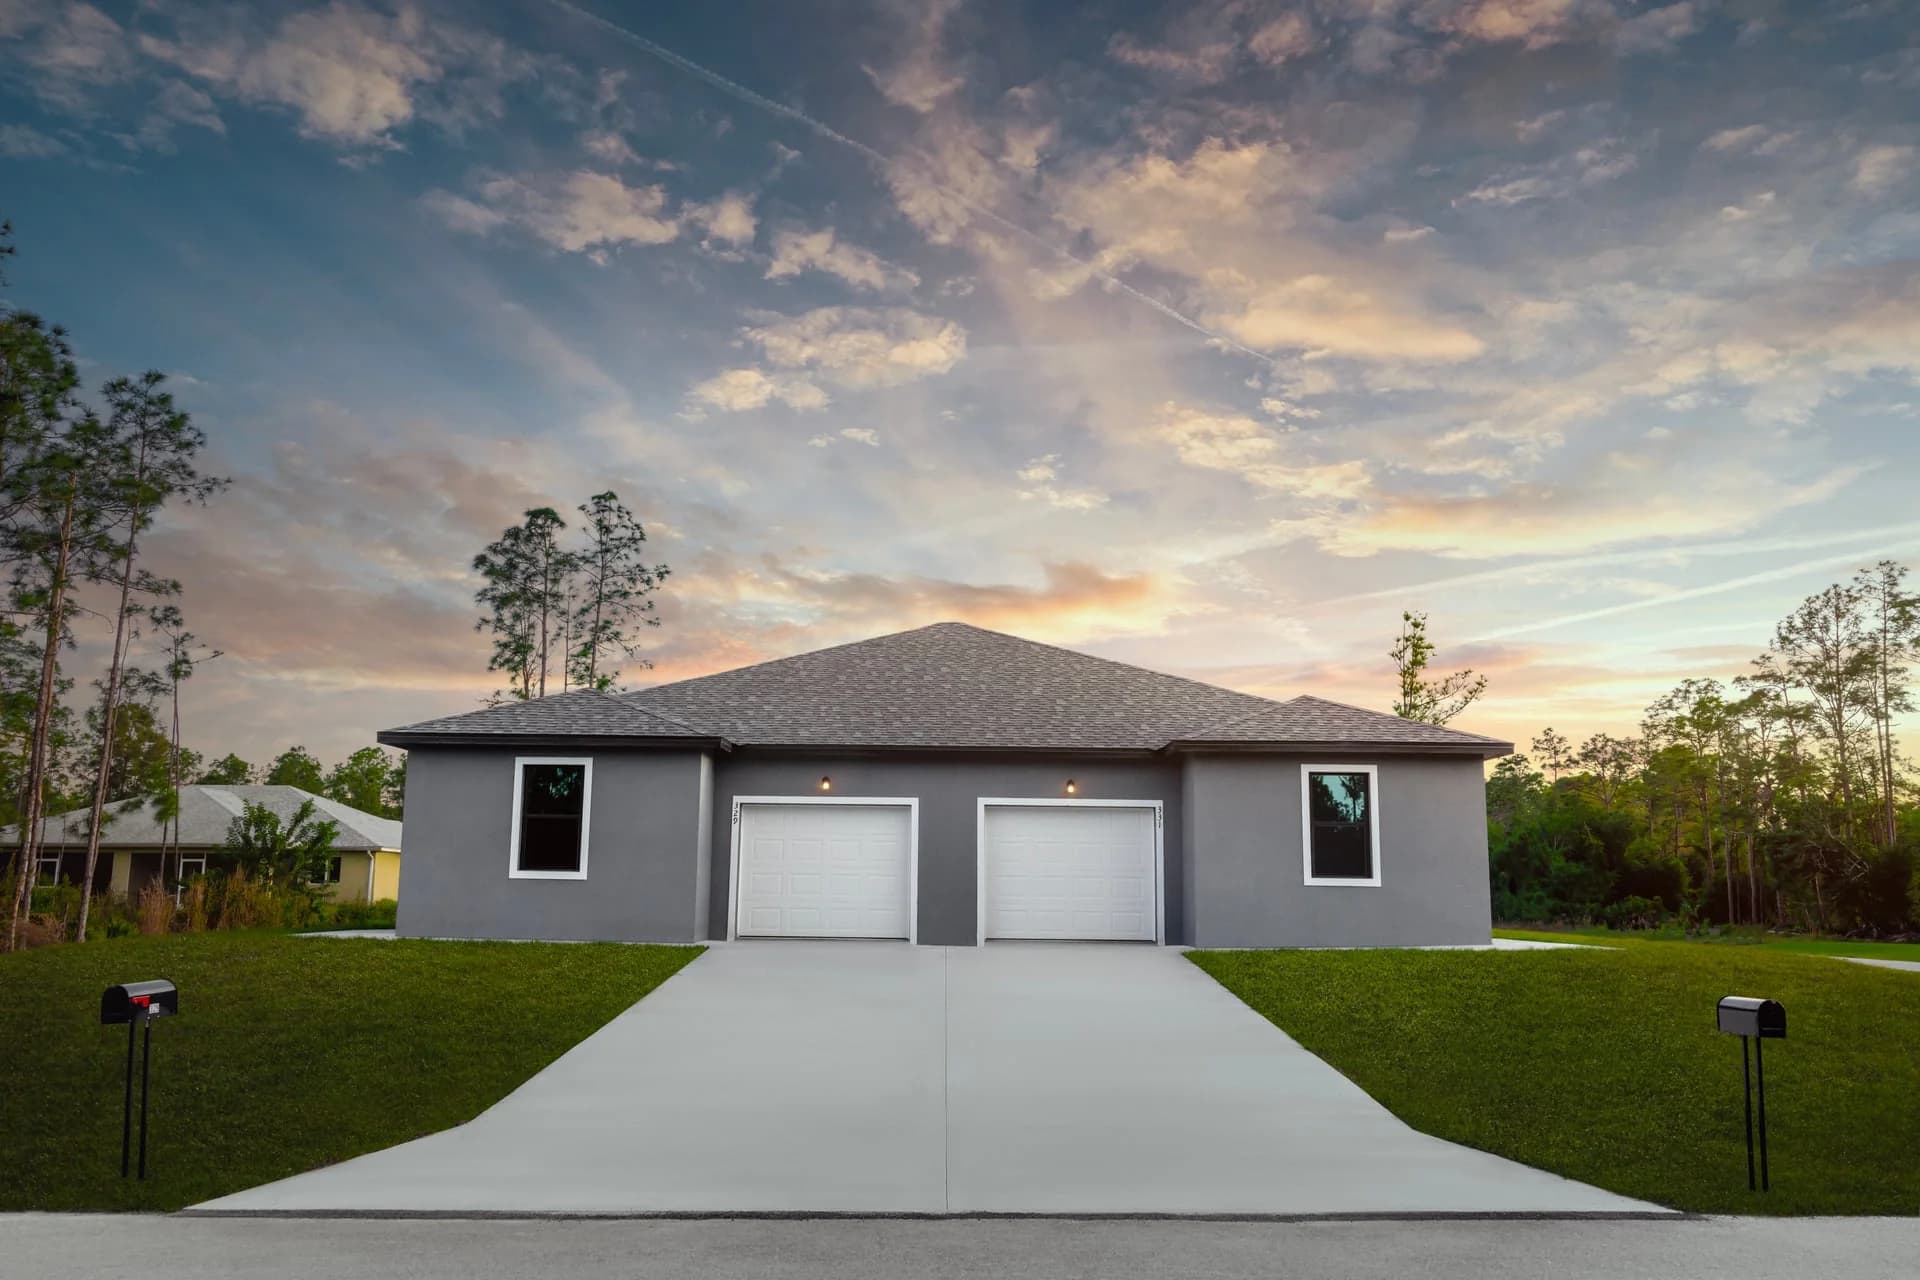
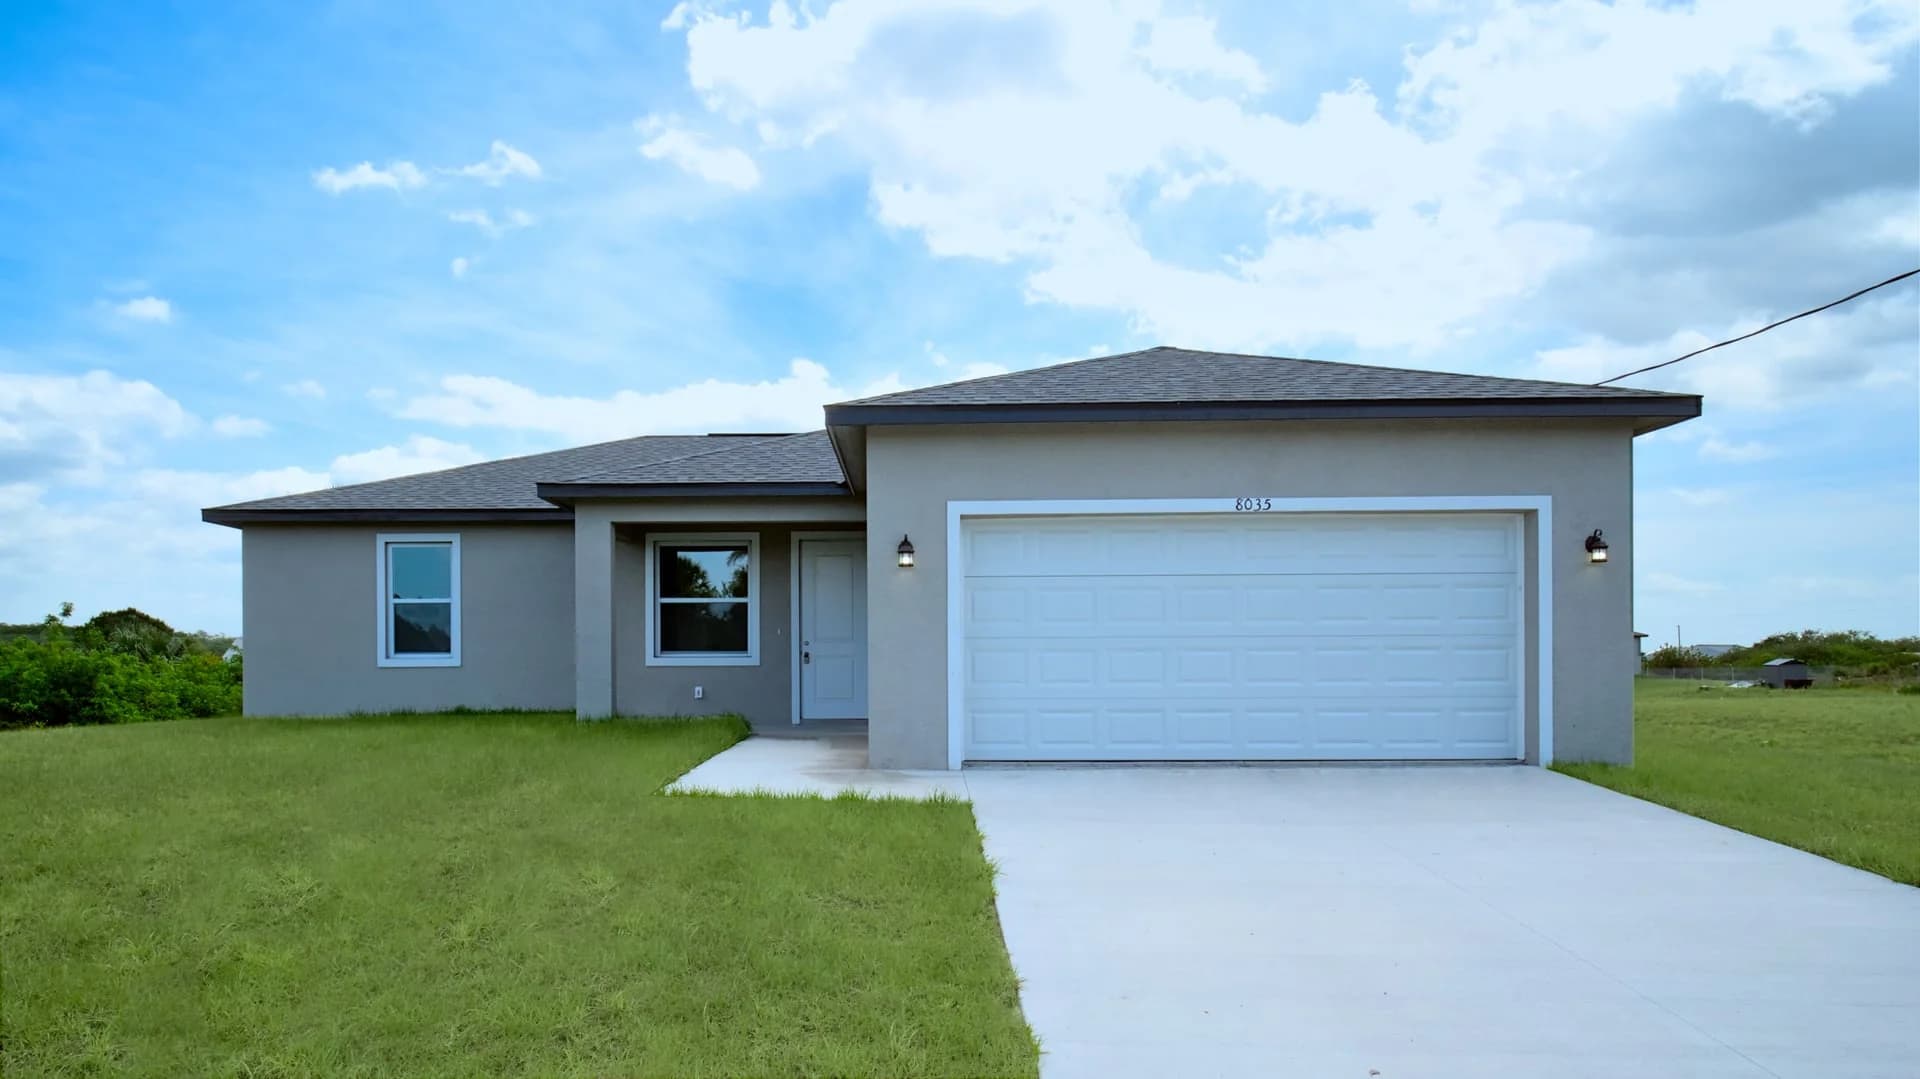
M.J. Newell Homes rent-to-own is $0 down and $0 closing costs to move into a new home now, without that mortgage. You rent, a portion of the payment is credited toward down payment and closing costs, and the price is locked. You purchase later.
Neither one is a promise that every applicant is approved. Last updated October 29, 2026.
USDA $0 down vs rent-to-own
| USDA Single Family Housing Guaranteed Loan | M.J. Newell Homes rent-to-own | |
|---|---|---|
| Who provides it | An approved lender, under USDA Rural Development rules | M.J. Newell Homes |
| Cash to move in | No down payment if the lender approves 100% financing. Closing costs and fees can still be due unless a seller credit or other allowed source covers them | $0 down and $0 closing costs to move in, under our published program |
| When you own | At closing | When you complete the purchase |
| Price | Negotiated purchase price and appraisal | Purchase price locked at the start of rent-to-own |
| Location test | The property must be in a USDA-eligible area on the current map | LaBelle and Lehigh Acres homes we offer on the program |
| Income test | Household income limits by county and family size, updated by USDA | We review income for the rent-to-own application. It is not the USDA limit |
| Credit | Lender and USDA standards | No bank loan required to start |
| Homestead clock | Can start once you own and occupy on January 1 | Starts after you take title, not on the rental move-in date |
| Best fit | You qualify now and want title immediately | You want the house now and a mortgage later, or a lender has said no for the moment |
Official program page: USDA Single Family Housing Guaranteed Loan Program. Eligibility map: USDA property and income eligibility. Maps and income limits change. A blog post cannot tell you that a specific lot is eligible this month. Look up the address.
What USDA will not do for you
USDA is not "zero cash" in every file. The guarantee is about the loan-to-value, up to 100% of appraised value for eligible cases. Prepaid taxes, insurance, and lender fees can still appear on a closing disclosure. Read the disclosure.
USDA is also not available just because a town feels rural. Lehigh Acres has grown quickly. Parts of a metro area drop off the map. Hendry County is more rural on a statewide map, and LaBelle is a common place buyers ask about, but the map is the authority. Do not let a salesperson in any state tell you "USDA is automatic in this county."
If you are an eligible veteran, sailor, or surviving spouse, a VA loan is a third zero-down mortgage path, with its own occupancy and entitlement rules. It is also a lender product. We can sell you the house. We do not issue the VA guaranty. FHA, by contrast, is usually a low-down-payment loan, not a zero-down loan.
What rent-to-own will not do for you
Rent-to-own will not put your name on the deed this week. It will not start homestead. It will not produce the November 4% tax discount until you are the owner paying the bill. Those owner benefits are real in Florida, and they wait for title. The explanation is in homestead for new residents and the early-payment discount.
Rent-to-own will let you occupy a new home while those pieces line up. Published purchase prices start at $316,900 in LaBelle. Monthly rent-to-own figures on the model pages start at $2,700 there. See how out-of-state buyers use the program.
How to choose
- If a lender has already said you qualify for USDA or VA, compare that payment, mortgage insurance or funding fee, and cash to close with a straight purchase of the same model. Owning sooner starts the homestead calendar sooner.
- If the lender wants a down payment you do not have, or more time on the job, apply for rent-to-own and keep the price locked.
- If you are not sure, bring both questions to the same visit. We would rather show you the house and the paperwork than stretch a loan product we do not control.
Frequently asked questions
Does M.J. Newell Homes guarantee a USDA loan in LaBelle?
No. We build and sell the homes, and we offer rent-to-own. USDA approval is between you, an approved lender, and Rural Development. Use the eligibility site for the address and your household size.
Can I start on rent-to-own and buy later with USDA?
You can plan to. The lender will underwrite you at the time you apply for the loan, against the rules in effect then, and the home must still be eligible. Your rent-to-own credits are a contract term with us. Ask the lender whether those credits can count as you hope. Get that answer in writing before you depend on it.
Is there a $0 down option if I have bad credit?
USDA and VA still have credit standards. Rent-to-own is the path we built for people a bank is not ready to finance. It is still an application. We review income and identity. It is not a no-questions lease.
Sources
- USDA Rural Development, Single Family Housing Guaranteed Loan Program
- USDA eligibility wizard
- U.S. Department of Veterans Affairs, VA home loans
See the homes: models. Start an application: rent to own.